Creditinfo Group acquires EveryData Group to expand presence across the Caribbean
Acquisition strengthens Creditinfo Group’s global footprint and accelerates investment in data and financial inclusion across the Caribbean
London, 6th August 2026 – Creditinfo Group, a global leader in credit information, data analytics and software solutions, today announced it has completed the acquisition of EveryData Group, a leading data, analytics and software company operating the Caribbean region’s primary credit bureaus.
Building on a longstanding partnership between the two organisations, the acquisition will enable Creditinfo Group to accelerate investment across the Caribbean, bringing enhanced technology and expanded data solutions to financial institutions and consumers throughout the region. Customers of both organisations will also benefit from greater technology integration and shared infrastructure across Creditinfo Group’s global network.
The acquisition further strengthens Creditinfo Group’s global presence, expanding its operations into the Caribbean and adding primary credit bureaus across Jamaica, Barbados, Guyana and the Eastern Caribbean Currency Union (ECCU), which comprises eight island nations: St Lucia, Antigua and Barbuda, St Kitts and Nevis, the Commonwealth of Dominica, Grenada, St Vincent and the Grenadines, Anguilla and Montserrat.
“This acquisition reinforces our commitment to helping build stronger financial ecosystems around the world,” said Satty Saha, Group CEO at Creditinfo Group. “EveryData has built an impressive business with a strong reputation across the Caribbean, and together we are well positioned to bring greater innovation and value to customers throughout the region. By combining our global expertise with EveryData’s deep local knowledge, we can accelerate the delivery of new products and technologies that improve access to finance and support economic growth.”
Kristinn (Kiddi) Agnarsson, CEO of EveryData Group, added “Joining Creditinfo Group marks an exciting new chapter for EveryData. Having worked closely together for many years, we already share a common vision for the future. Becoming part of Creditinfo’s global network will enable us to invest further in our products, our people and our customers, while continuing to deliver the trusted local expertise our markets rely on.”
Reynir Finndal Grétarsson, Chairman of EveryData Group, said “Creditinfo Group is the ideal long-term home for EveryData. We are proud of what EveryData has achieved across the Caribbean, and we are confident that as part of Creditinfo Group, the business is exceptionally well positioned to build on this strong foundation and continue its success for many years to come.”
Over the coming years, Creditinfo Group will continue investing in technology, talent and innovation across the Caribbean, helping financial institutions make better-informed decisions while expanding financial inclusion and supporting sustainable economic development across the region.
-END-
About Creditinfo
Established in 1997 and headquartered in London, UK, Creditinfo is a provider of credit information and risk management solutions worldwide. As one of the fastest-growing companies in its field, Creditinfo facilitates access to finance, through intelligent information, software and decision analytics solutions.
With more than 30 credit bureaus running today, Creditinfo has the most considerable global presence in this field of credit risk management, with a significantly greater footprint than competitors. For decades it has provided business information, risk management and credit bureau solutions to some of the largest, lenders, governments and central banks globally to increase financial inclusion and generate economic growth by allowing credit access for SMEs and individuals.
For more information, please visit www.creditinfo.com, www.everydata.com
Creditinfo Group Named Culture100 Award Winner
Creditinfo is incredibly proud to share that Creditinfo has been recognised as a Culture 100 Award winner and named “Most Thriving Company To Work For”.
Read more about our Culture 100 recognition: https://www.readmaya.com/spotlight-creditinfo
This recognition celebrates organisations that are building exceptional workplace cultures where people are empowered to grow, collaborate, innovate, and make a meaningful impact.
At Creditinfo, our culture is not defined by policies, it is shaped by our people. Across more than 40 countries, our teams bring diverse perspectives together with a shared purpose: using trusted data and technology to enhance financial inclusion for our communities.
This award is a testament to every colleague who lives up to our values of Respect, Innovation and No-nonsense every day and contributes to making Creditinfo an inspiring place to work.
Thank you to our incredible team for making this achievement possible! we are excited to continue building a workplace where people and ideas thrive.
Creditinfo and NOTO partner to expand market access to modern fraud and AML controls for banks, fintechs and lenders
Collaboration combines data and tech to strengthen financial crime prevention
12th November 2025 – Creditinfo, a global provider of credit risk and data intelligence, and NOTO, an enterprise platform for fraud prevention and anti-money laundering (AML), today announced a partnership to bring modern, data-rich financial crime controls to banks, fintechs and lenders across multiple markets. The agreement pairs Creditinfo’s in-market coverage and data expertise with NOTO’s adaptable decisioning and case-management platform, aiming to enhance risk controls while preserving a seamless customer experience.
Financial institutions continue to face higher fraud losses, sharper regulatory scrutiny, and a highly dynamic environment that demands greater agility, while onboarding speed expectations continue to rise. The partnership focuses on measurable outcomes – stronger KYC and screening, better detection and monitoring, and streamlined investigations – delivered in a way institutions can roll out and scale without major IT upheaval.
Partnership highlights:
- Market access + enablement: Creditinfo distribution and NOTO technology delivered together, enabling faster rollout
- Outcome focus: Will reduce fraud losses and false positives, strengthen AML readiness, and shorten time from pilot to production.
- Operational fit: Simple to deploy where it will have the most impact then extend across the lifecycle as requirements evolve.
Rob Meakin, Fraud and Identity Director at Creditinfo said: “Clients need practical improvements they can deploy and adapt quickly. By combining high-fidelity risk and trust signals from Creditinfo with NOTO’s agile, high capacity, low latency technology stack we’re giving financial institutions a balanced, risk-aware method of strengthening KYC, screening and monitoring that can be easily tailored to local conditions.”
Ivan Stefanov, CEO and Co-Founder at NOTO, said: “Creditinfo brings the data; NOTO turns it into decisions. Financial institutions don’t need another dashboard—they need decisions they can trust in milliseconds. By combining Creditinfo’s depth of bureau and alternative data with NOTO’s real-time risk decisioning, we give clients a single risk view across onboarding, fraud, and AML. The result: Less financial crime. More business.”
The joint offering is now available via Creditinfo and NOTO. Organisations can contact either company for details.
END.
About Creditinfo
Established in 1997 and headquartered in London, UK, Creditinfo is a provider of credit information and risk management solutions in over 30 countries worldwide. As one of the fastest-growing companies in its field, Creditinfo facilitates access to finance, through intelligent information, software, and decision analytics solutions.
About NOTO
NOTO is a modular, scalable, and adaptable platform for fraud prevention and AML compliance, built by experts to deliver measurable outcomes across the customer lifecycle.
How Economic Uncertainty Manifests in Payment Defaults Across the Baltics
In recent years, the economic environment in the Baltics has become faster-moving and less predictable. Previously, it took 12–18 months after an economic turning point for payment difficulties among companies and individuals to appear in the payment default register. Today, this happens much sooner — often within 6–9 months, and in some sectors even within a single quarter.
Payment Defaults as an Early Warning
Creditinfo manages the payment default register, which collects daily data from banks, leasing companies, utilities, telecoms, and other businesses. This provides a comprehensive overview of market payment behavior trends.
However, not all payment defaults become publicly visible, which makes the aggregated data in the register a valuable early indicator — showing shifts in the economy before they surface publicly or are reflected in official economic statistics.
Two Waves: Companies First, Individuals Later
Based on payment default data, economic difficulties typically unfold in two phases:
- First, companies. When costs rise or customers delay payments, businesses face liquidity challenges — sometimes visible within a single quarter.
- Then, households. Initially, savings and financial buffers help, but over time, pressure reaches individuals, leading to unpaid bills.
In other words, a rise in company payment defaults often serves as an early warning that the economy is entering a more difficult phase.
Three Countries, Three Speeds
While overall trends are similar across the Baltic countries, shaped by global economic developments, the pace and timing differ:
- Estonia tends to see payment defaults appear more quickly after economic challenges emerge, but both companies and individuals also recover and repay debts faster than elsewhere in the Baltics.
- Latvia shows greater seasonality in debt repayment and reporting across certain sectors compared to its neighbors.
- Lithuania tends to experience risks materializing into payment defaults later than the other Baltic states — reflecting higher resilience — but once defaults occur, they persist longer, meaning problems take more time to resolve.
Which Sectors Show Changes First?
The most sensitive sectors include:
- Construction, where rising costs and changes in financing conditions have an immediate impact.
- Transport, logistics, and wholesale, which quickly feel shifts in the rhythm of the economy.
- Retail and services, where payment difficulties emerge as consumer purchasing power declines.
What Does This Mean for Businesses?
As the economy changes faster than before, annual risk assessments are no longer enough. Companies that regularly use payment default data in evaluating partner and customer credit risk can respond more quickly — by adjusting credit limits, updating terms, or planning sales volumes more realistically.
The era when risks evolved over years is over — today, success belongs to those who spot changes first and adapt fastest.
In Summary
In the Baltics, economic and credit risks now shift quarter by quarter, not year by year. Companies that use payment default data as early warning signals can keep a close eye on their business environment — and stay one step ahead of the market.
The Importance of Trust in Digital Interactions: The Cornerstone of a Digital Economy
There’s a diversity in maturity in digitization across the globe – from markets that are almost universally digital, through markets with developing digital economies, to markets with embryonic digital ecosystems. Mature economies typically have more mature controls but remain attractive to fraudsters because of the scale of opportunity – emerging digital economies typically have less robust ecosystems and are attractive because of the inherent vulnerabilities in the controls – with a promise for future growth.
The anonymity and distance that digital platforms afford make it easier for fraudsters to operate undetected.
For bad actors, the business model is scalable – in a digital economy the unique skills of Frank Abagnale Jr (of “Catch Me If You Can” fame) become redundant. The ready availability of personal data through vast data breaches and social engineering, and online access to digital channels present an attractive proposition for the enterprising fraudster.
In fact, cybercrime has risen dramatically alongside digital transformation, with fraud rates increasing globally – and we’re increasingly seeing collaboration between cybercrime, fraud, organised crime and money laundering. Organizations face mounting challenges in protecting their digital infrastructure and customers from fraudulent activities. From identity theft to financial scams, fraudsters are leveraging a wide array of tactics to deceive individuals and organizations.
The digital economy’s vulnerability to fraud presents significant risks, not only for organizations, but also for consumers. When fraud occurs, it undermines the trust that is essential to the functioning of the digital economy. If consumers and businesses cannot trust the digital services they engage with, it will slow adoption, hinder growth, and damage reputations. Therefore, mitigating fraud risk is not just about protecting individual interactions – it’s about maintaining the integrity of the entire digital ecosystem.
The importance of trust in digital interactions cannot be overstated. From e-commerce to financial services and beyond, trust is the foundation upon which all successful digital interactions are built. At the core of this trust is the concept of identity verification. In a world where interactions are increasingly conducted online, it’s critical to ensure the presented identity is a real-world identity, not synthetic – and that the individual presenting the identity is the owner of that identity.
The need to assert identity in digital engagements goes beyond basic security – it forms the bedrock of confidence that drives the entire online ecosystem. Whether consumers are signing up for a new banking service, purchasing products, or enrolling in educational courses, verifying the authenticity of their identity is paramount. Identity verification serves not only to protect individuals but also to secure businesses from fraudulent activities, which, in turn, strengthens the broader digital economy.
The Role of Identity Verification in Mitigating Fraud Risk
At the heart of reducing fraud risk lies robust identity verification. This process ensures that the individual engaging with a digital platform is who they claim to be. It is a crucial step that lays the groundwork for every subsequent transaction, providing a layer of protection for both consumers and businesses. Without reliable identity verification, any digital interaction is susceptible to being manipulated by malicious actors.
Identity verification can be achieved through a variety of techniques, including biometric verification, document verification, and multi-factor authentication. These methods allow businesses to verify that a person is genuine, providing them with the confidence to proceed with transactions. This, in turn, enables a safer and more reliable digital environment for everyone involved.
However, while basic identity verification is a critical first step, it is only part of the solution.
The Power of Layering Fraud Defences
In a digital economy, an identity is far more than a name, address, date of birth and national id number.
From basic digital identity attributes such as mobile numbers, email addresses and IP addresses, through payment attributes such as bank details and credit card numbers, through connected messaging apps and service accounts, through device attributes such as screen size, make, model, time zone, location, installed apps, through biometric attributes such as facial patterns, to behavioural attributes such as physical device interactions. A digital identity is an extensive and interconnected web of many attributes.
The real strength in mitigating fraud risk lies in combining multiple layers of defence – a multifaceted approach that examines not only the traditional identity attributes, but the wider digital footprint and the connections between attributes across the identity graph. Consistency and conformity to normalised patterns help establish greater trust – inconsistency and anomalous patterns indicate greater risk. Machine learning and artificial intelligence techniques are increasingly used to examine attribute patterns – generating increasingly performant models.
The power of a layered approach lies in managing the balance between making life difficult for bad actors and removing friction in genuine interactions. In a digital economy consumers become increasingly intolerant of any friction in their interactions with organisations. Where consumers encounter even minor friction, they will abandon the sales process and look for alternative providers – in a competitive market, the winners will be the businesses who deliver the easiest way to interact – but without appropriate fraud defences, success will be short lived.
More accurate multifaceted risk assessments can be implemented based lighter data capture, drawing insights from a broad range of sources, reducing CX friction and abandonment, readily securing greater trust, more accurately exposing risk.
Summary
As the digital landscape continues to evolve, organizations must prioritize trust as the cornerstone of their interactions with consumers. Robust identity verification and a layered approach to fraud prevention are not just best practices – they are essential for maintaining the integrity of the digital economy. By effectively combining multiple layers of defence, businesses can balance security with convenience, reducing fraud risk without sacrificing customer experience. In the end, fostering trust in digital engagements is the key to enabling sustained growth and success in an increasingly complex and competitive online ecosystem.
For more information, please visit: www.creditinfo.com
or email info@creditinfo.com
Author : Robert Meakin – Director, Fraud & ID, Creditinfo Group
Creditinfo Launches New Global Fraud & ID Solution
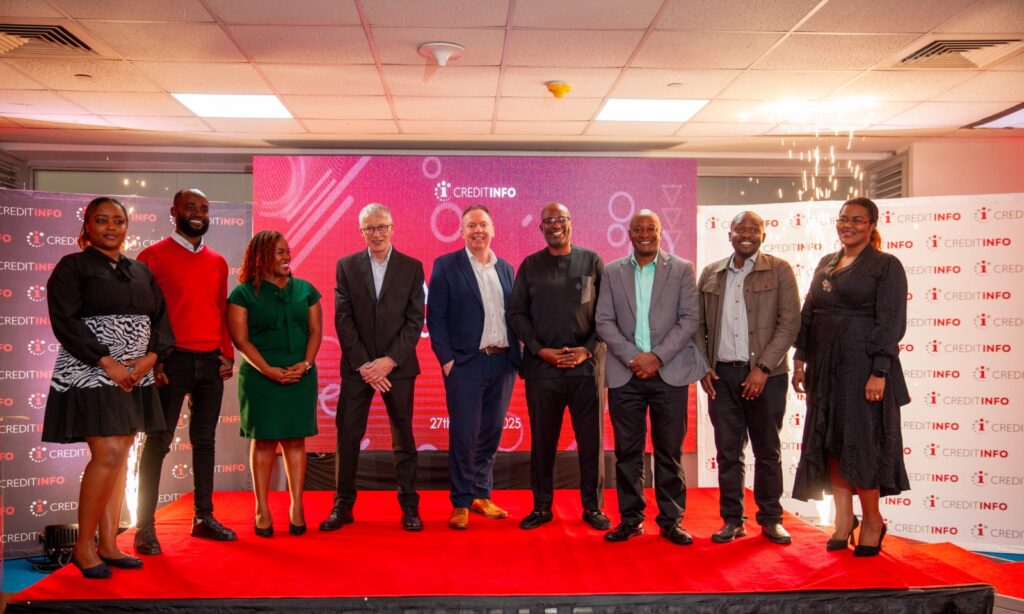
Creditinfo’s new solution supports clients in mitigating the impact of fraud and supporting organisational growth.
London – 27th March 2025: Creditinfo, a global service provider for credit information and risk management solutions, has today announced the launch of its global identity, know your customer (KYC), and fraud and ID solution, set to help organisations tackle financial crime.
The overall global economic impact of financial crime has been estimated to be $5 trillion. What’s more, according to the 2024 Nasdaq global financial crime report, fraud losses totalled $485.6 billion worldwide, from fraud scams and bank fraud schemes alone. As such, organisations face a series of challenges, from eroding profit margins to reputational risks to data breaches. Creditinfo’s solution helps organisations to address these challenges by using credit bureau data, government information services, and other registries to establish trust in presented identities, without negatively impacting the customer experience.
The solution integrates identity proofing, digital risk signals and comprehensive international and domestic watchlists to deliver strong KYC compliance and reduce the risk of fraudulent activity. It also enables businesses to streamline risk management and ensures they meet stringent customer due diligence requirements under anti-money laundering (AML) regulations.
As a global solution, it is tailored to meet the unique needs and maturity-levels of different markets. By accounting for these differences, organisations that use the solution can adapt their fraud prevention strategies to specific local risks, strengthening security and promoting financial inclusion.
Creditinfo has appointed Rob Meakin as Director of Fraud & Identity to head up this service. He brings extensive experience in fraud prevention, identity management, and financial services. Meakin will lead efforts to help organisations counter fraud – leveraging advanced technologies and data analytics to enhance the customer experience and strengthen fraud and AML controls.
Rob Meakin, Director of Fraud and Identity at Creditinfo, said: “The growing presence of organised financial crime is significantly hindering economic growth on both a local and global scale, costing businesses huge sums of money each year – in fraud losses, lost sales and operational costs. That’s why, at Creditinfo, we’re pioneering a solution that provides a way for organisations to manage risk and maintain compliance while facilitating secure and easy access to financial products and services for consumers.”
John Cannon, Chief Commercial Officer at Creditinfo said: “By removing friction from both traditional and digital onboarding and origination processes, our solution helps organisations reduce fraud, improve conversion rates, and drive top-line growth while ensuring a seamless customer journey. As we strive to expand our global reach and enhance financial access for millions of consumers and businesses worldwide, having Rob join our team is an invaluable advantage, strengthening both our security capabilities and our ability to deliver innovative solutions.”
-END-
About Creditinfo
Established in 1997 and headquartered in London, UK, Creditinfo is a provider of credit information and risk management solutions worldwide. As one of the fastest-growing companies in its field, Creditinfo facilitates access to finance, through intelligent information, software and decision analytics solutions.
With more than 30 credit bureaus running today, Creditinfo has the most considerable global presence in this field of credit risk management, with a significantly greater footprint than competitors. For decades it has provided business information, risk management and credit bureau solutions to some of the largest, lenders, governments and central banks globally to increase financial inclusion and generate economic growth by allowing credit access for SMEs and individuals.
For more information, please visit www.creditinfo.com
For inquiries email rob.meakin@creditinfo.com
Central Bank of Seychelles awards Creditinfo contract to Develop and Implement a new Credit Information System (SCIS)
PRESS RELEASE
Victoria– September 11, 2024 – The Central Bank of Seychelles (CBS) has today launched the Seychelles Credit Information System (SCIS) in accordance with the Credit Reporting Act, 2023, to improve credit information sharing across the financial system.
The SCIS will be administered by CBS, which will be responsible for overall supervision of the operation of the system, as well as providing awareness on the system and its governing law. The contract to develop and implement the SCIS was awarded to Creditinfo CEE a.s., a company based in the Czech Republic, through an open bidding method as per the CBS procurement process in April 2021.
The SCIS – which replaces the previous Credit Information System established under the Credit Reporting Regulations 2012 – is an improved credit information system which will enhance credit reporting and data exchange between participating institutions. It incorporates automated features requiring minimal manual processing, hence mitigating potential risks of inaccuracies in the credit information of customers.
The current participants of the SCIS include the commercial banks, Seychelles Credit Union, Development Bank of Seychelles and the Housing Finance Company (HFC). The SCIS will continue to expand with the addition of other participants through a phased approach, to include Government entities, utility companies, hire purchase and credit sales, financial leasing companies, and insurance companies. The addition of these other entities – that are also engaged in activities that provide for payment arrangements – will give a more accurate indication of the repayment history and level of indebtedness of customers, information which is essential in the decision-making process for granting credit and loan facilities.
To note that only participating institutions can access the credit information of an individual, at the consent of the individual, in compliance with the Credit Reporting Act, 2023. Individuals holding accounts with these institutions will also be able to access their own credit report through the Customer Credit Portal, which is expected to be launched in the first quarter of 2025.
To watch a news clip of the event, click here.
Visit our websites for more information
ENDS.
Open Banking Solutions at Creditinfo
In 2020 Creditinfo Group decided to be part of the Open Banking initiative by starting to investigate the options of using customers’ bank account statements in their offering. The account information service is based on the PSD2 directive. For known reasons, it is not possible and acceptable to have access to customer bank account data without consent.
Creditinfo have tackled the opportunity in two different ways. In the Baltics and Iceland, the chosen route was to apply for an FSA licence to offer end-to-end customer account statements transfer from their home bank to a third party, from whom the customer applies for credit , e.g. car loan. In the Czech Republic and Slovakia namely due to the long and cost-intensive process of “passporting” CI’s Estonian license, the chosen route was collaboration with a local technical partner called Sokordia Tech.
A little bit more about above-mentioned two ways to offer Open Banking solutions in Creditinfo Group.
In 2021 Spring, Creditinfo Estonia received permission from the Financial Supervision Authority to start offering account information services in Estonia, which later in Autumn expanded to the markets of Latvia and Lithuania. Today, Creditinfo has been offering the account information service in the Baltic market for almost three years. Creditinfo have real-time access to the transaction data of customers of banks and financial institutions using a secure data transmission channel and customer consent.
In Spring 2024, Creditinfo Estonia finalised the Iceland licence application process from Estonian FSA and can officially offer account information service in Iceland.
Beside regulative and compliance part, Creditinfo also has full technical integration and capability in developing categorization when offering account informatoin service. With opportunity to access customers bank account data, the aim is to offer more transparent credit risk evaluation to customers and third parties, who find high value from the knowledge of their customers account information to make data-driven, intelligent credit and business decisions.
As mentioned above, Creditinfo also have Open Banking cooperation and partnership in the Czech Republic and Slovakia with fintech company Sokordia Tech, teaming up to capitalize on Creditinfo’s market position whilst leveraging Sokordia Tech’s AISP and PISP licenses and Open Banking services platform to provide PSD2/Open Banking services to several financial services clients in the market.
In the Czech Republic and Slovakia market, Creditinfo currently has 5 customers utilizing the Open Banking platform, processing more than 1.2 million open banking transactions per month. Depending on the specific requirements, pain points, and use case of the Client, Creditinfo has developed a “Categorization In-a-Box” , Multi-Service platform called Transaction Analysis Service replete with 40,000 pre-installed business rules that can sit atop and work with any Open Banking Open APIs in any country. The service is comprised of 6 unique methods/services (AIS+CIS+PIS) & PDF tools via one API as detailed below:
- PSD2parser: extracting raw data from PSD2 bank statements
- PSD2tags: tag each bank transaction with one to N identifying tags
- PDFparser: Extracting raw data from PDF bank statements
- PDFtags: Tag each bank transaction with one to N identification tags
- 1UnitPay: Verification PSD2 payment (the advantage is that the payment is made in one step with statement extraction)
- Bank Account Views: Repeated viewing of bank accounts without the need for customer re-authentication
Together with our partner Sokordia Tech, we currently have Open Banking APIs and are able to provide all these services under one single API for the following countries: Czech Republic, Slovakia, Hungary, Romania, and Poland.
Development work on the 3rd generation of the Transaction Analysis Service is currently in development, highlighted by:
- Deeper AI involvement in processes & rules & analysis
- Expansion of new online data inputs into transactional analytics
- Multi-language analytical tools
- GUI for clients to manage and report transactional analytics themselves
For more information, please visit: www.creditinfo.com
Authors:
Seth Marks – Regional Director Central, Eastern & Southern Europe, Creditinfo Group
Ivo Vallau – Open Banking Product Manager, Creditinfo Group
Creditinfo appoints TransUnion veteran as new Global Chief Commercial Officer
Seasoned commercial leader, John Cannon, looks to use wealth of financial and executive leadership experience in new role to unlock new value for customers and drive Creditinfo’s international growth
London – 18 April 2024: Creditinfo, a global service provider for credit information and risk management solutions, has today announced the appointment of John Cannon as its Global Chief Commercial Officer (CCO). With over 25 years of experience in finance and credit bureaus, John will spearhead the strategy and execution behind Creditinfo’s solutions and products for all 30 of its credit bureaus, which are spread across 50 different countries.
John brings almost three decades of experience in leading top-performing teams, delivering pioneering solutions, and galvanising high-value market leading companies within the global financial community. A reputable industry expert, John led Transunion’s GFS business for international regions and has spent the last couple of years as an advisor to Private Equity firms in addition to helping scale early stage technology companies, most recently Xapien.
As CCO of Creditinfo, John will draw on his extensive sector knowledge and experience to leverage Creditinfo’s technology and data to push innovation forward and ensure it meets customer expectations and needs. He will play a key part in promoting financial inclusion globally and in doing so bolster Creditinfo’s international growth. In his new role, John will also be responsible for delivering the right products and services to Creditinfo’s customers to maximise value, as well as identifying new business opportunities.
John Cannon, newly appointed Global Chief Commercial Officer at Creditinfo said: “I’m delighted to join Creditinfo, a company that is committed to enriching people’s lives through unlocking access to financial inclusion. This, and its international culture, is what drew me to the company. I look forward to working with the remarkable Creditinfo team to support the next phase of its growth journey.”
Satrajit Saha, Global CEO at Creditinfo said: “With firm roots in the global financial industry and a strong track record as a senior executive leader, John is an excellent addition to our senior leadership team. As we look to expand our global footprint and facilitate access to finance for millions of consumers and businesses worldwide, having John on board is a huge advantage, not only for our own innovation and growth but also for our customers as they turn to us to provide worldclass and transformative solutions and products.”
John will report directly to Satrajit Saha, Creditinfo’s Global CEO.
-END-
About Creditinfo
Established in 1997 and headquartered in London, UK, Creditinfo is a provider of credit information and risk management solutions worldwide. As one of the fastest-growing companies in its field, Creditinfo facilitates access to finance, through intelligent information, software and decision analytics solutions.
With more than 30 credit bureaus running today, Creditinfo has the most considerable global presence in this field of credit risk management, with a significantly greater footprint than competitors. For decades it has provided business information, risk management and credit bureau solutions to some of the largest, lenders, governments and central banks globally to increase financial inclusion and generate economic growth by allowing credit access for SMEs and individuals.
For more information, please visit www.creditinfo.com
Overview: Creditinfo Estonia’s Payment Default Registry in 2023
Creditinfo Estonia’s Payment Default Register was established in 2001 by Estonian banks, being the largest and oldest register in Estonia that gathers consistent and high-quality debt information. The register of payment defaults helps Estonian entrepreneurs make the right credit decisions and enables the application of the principle of responsible lending.
The largest contributors of payment defaults continue to be from the financial sector
In 2023, a total of over 700 companies entered payment defaults in the register. The TOP entrants by activity were:
- Credit institutions
- Financial service providers
- Collection service providers
- Telecom companies
During the entire year, more than 100,000 new payment defaults were added to the register by companies, of which 91% were private payment defaults. Payment defaults of legal entities were published in a total of nearly 9,200 cases.
There are tens of thousands of people with payment defaults in Estonia
As of the end of 2023, there were nearly 57,000 individuals with active payment defaults.
During the liquidation of the debt, the current default is marked as closed – in 2023, there were 111,000 private individuals with a closed payment default. A closed payment default indicates that the debt has been paid, but at the same time it warns the creditor that the person has had problems paying bills in the past and this allows for a more accurate assessment of his creditworthiness. NB! In the case of private individuals, closed payment defaults are published for up to 5 years after the payment default has ended.
As of the end of 2023, there were almost 20,000 legal entities or companies-institutions with active payment defaults.
There were nearly 33,000 legal entities with closed payment defaults. NB! In the case of companies, the information provided will be published for another 7 years after the end of the default.
There are more than 150 thousand active payment defaults in the register
By the end of 2023, there were nearly 130,000 active payment defaults in the Payment Default Register by individuals with payment defaults. The average payment default amount, or debt, of a private person is €2,514. There were almost 363,000 private individuals with payment defaults that were closed.
At the end of 2023, there were approximately 40,000 active defaults of legal entities. There were almost 65,000 closed defaults of legal entities.
The number of valid payment defaults has increased
In total, there were nearly 171,000 active payment defaults published in the Payment Default Register. If we add to this the information on payment defaults in the closed and disputed status, the total number of payment defaults in the Payment Default Register is 600,697, which has increased by approx. 9% compared to 2022.
At the same time, the effectiveness of the Payment Failure Register is maintained. Of all payment defaults that have reached publication, one in four, or 26%, is paid immediately within the first month, and half (47%) within the first three months after publication.
The disclosure has the greatest impact on the debts of the financial sector – 36% of all defaults disclosed by banks and leasing companies are paid already within the first month and almost 63% within the first three months.
Visit www.creditinfo.ee for more information.